The Four Types of PMI: Which One Will You Have?

Jennifer Hernandez • January 10, 2025

When it comes to buying a home with less than a 20% down payment, Private Mortgage Insurance (PMI) almost always becomes a part of your monthly payment. Did you know there are four types of PMI? Each option has unique features, so understanding these can help you make the best decision for your financial situation. In this guide, we'll break down the four types of PMI and share with you which ones fit your situation.


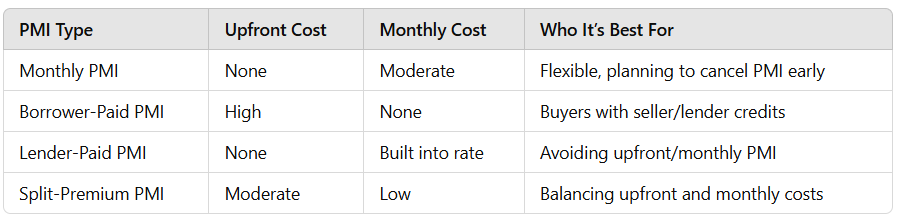
1. Monthly PMI: The Most Popular Choice

Monthly PMI is the most common option. Here’s how it works:

  • Cost: Calculated as a percentage of the loan amount, divided by 12, and added to your monthly payment.
  • Benefits: This is an excellent choice for borrowers planning to pay off PMI early by reaching 80% loan-to-value (LTV) through extra payments, bonuses, or selling another property.
  • Why Choose It? If you’re looking for flexibility and don’t want a long-term PMI commitment, monthly PMI is a straightforward and popular choice.


2. Borrower-Paid PMI (Upfront PMI)

With borrower-paid PMI, you pay a one-time upfront fee instead of monthly payments.

  • Cost: A single premium paid at closing. This fee can be:
  • Covered by seller credits
  • Paid by lender credits
  • Paid out of pocket by the borrower
  • Benefits: No monthly PMI reduces your overall mortgage payment.
  • Why Choose It? Ideal for buyers who receive seller or lender credits or want to keep monthly payments lower.


3. Lender-Paid PMI

Lender-paid PMI eliminates the monthly PMI payment by slightly increasing your mortgage interest rate.

  • Cost: An increased interest rate (usually 0.3% to 1% higher) depending on your credit score and down payment.
  • Benefits: No out-of-pocket PMI payments or monthly add-ons.
  • Why Choose It? It’s less common but may be an option if you want to avoid monthly PMI without paying an upfront fee. However, keep in mind the higher interest rate over the life of the loan, which does increase your monthly payment as well.


4. Split-Premium PMI

Split-premium PMI combines upfront and monthly PMI payments.


  • Cost:
  • A portion is paid upfront at closing (can be covered by seller or lender credits).
  • The remainder is paid monthly.
  • Benefits: Reduces your monthly PMI while requiring a smaller upfront payment than borrower-paid PMI.
  • Why Choose It? This option is less popular due to its complexity but can work well for buyers looking to balance upfront and ongoing costs.


How to Choose the Best PMI for You

The right PMI option depends on your financial goals and situation:

  • Are you looking to reduce monthly payments? Consider Borrower-Paid PMI or Split-Premium PMI.
  • Want flexibility to cancel PMI early? Go with Monthly PMI.
  • Prefer no upfront or monthly PMI payments? Explore Lender-Paid PMI.

Steps to Take:

  1. Work with a Local Lender: Your lender will guide you through PMI options and provide estimates tailored to your loan amount and credit score.
  2. Compare Costs: Ask for a detailed breakdown of each PMI option in a spreadsheet or chart to see how they affect your payment and overall loan cost.
  3. Get Pre-Approved: Pre-approval is essential to understanding your PMI costs and securing the best mortgage rate.


Understanding the four types of PMI can save you money and ensure your mortgage aligns with your financial plans. Start by talking to a trusted lender, at Legacy Mutual Mortgage, to learn about your PMI options.

Ready to explore your PMI options?


Helpful Resources:


Have questions about PMI or the home-buying process? Don’t hesitate to reach out—
I’m here to help you find the best solutions for your unique needs. Whether you're just starting your journey or finalizing your plans, let’s work together to make your dream of homeownership a reality!

Laptop showing fake wiring instructions beside a house model and scam alert phone.
By Jennifer Hernandez • October 27, 2026
Learn how to protect your down payment from wire fraud when buying a home, including warning signs and safe steps to verify wiring instructions.
Couple reviewing mortgage documents at home with city view.
By Jennifer Hernandez • October 20, 2026
Learn how to navigate the homebuying process, understand mortgage options, and make confident decisions when buying a home.
Texas homeowners insurance policy with a house model, umbrella, and Texas map.
By Jennifer Hernandez • October 13, 2026
Homeowners insurance premiums are skyrocketing across Texas. Discover what’s causing the increase, what you can do to protect yourself, and how to shop smart for coverage in 2025 and beyond.
Real estate agent showing a bright modern living room to a couple in a sunlit open-plan home
By Jennifer Hernandez • September 29, 2026
Explore how sellers are aiding buyers in Houston's market. Get expert guidance to find your dream home today!
LWJ
By Jennifer Hernandez • September 22, 2026
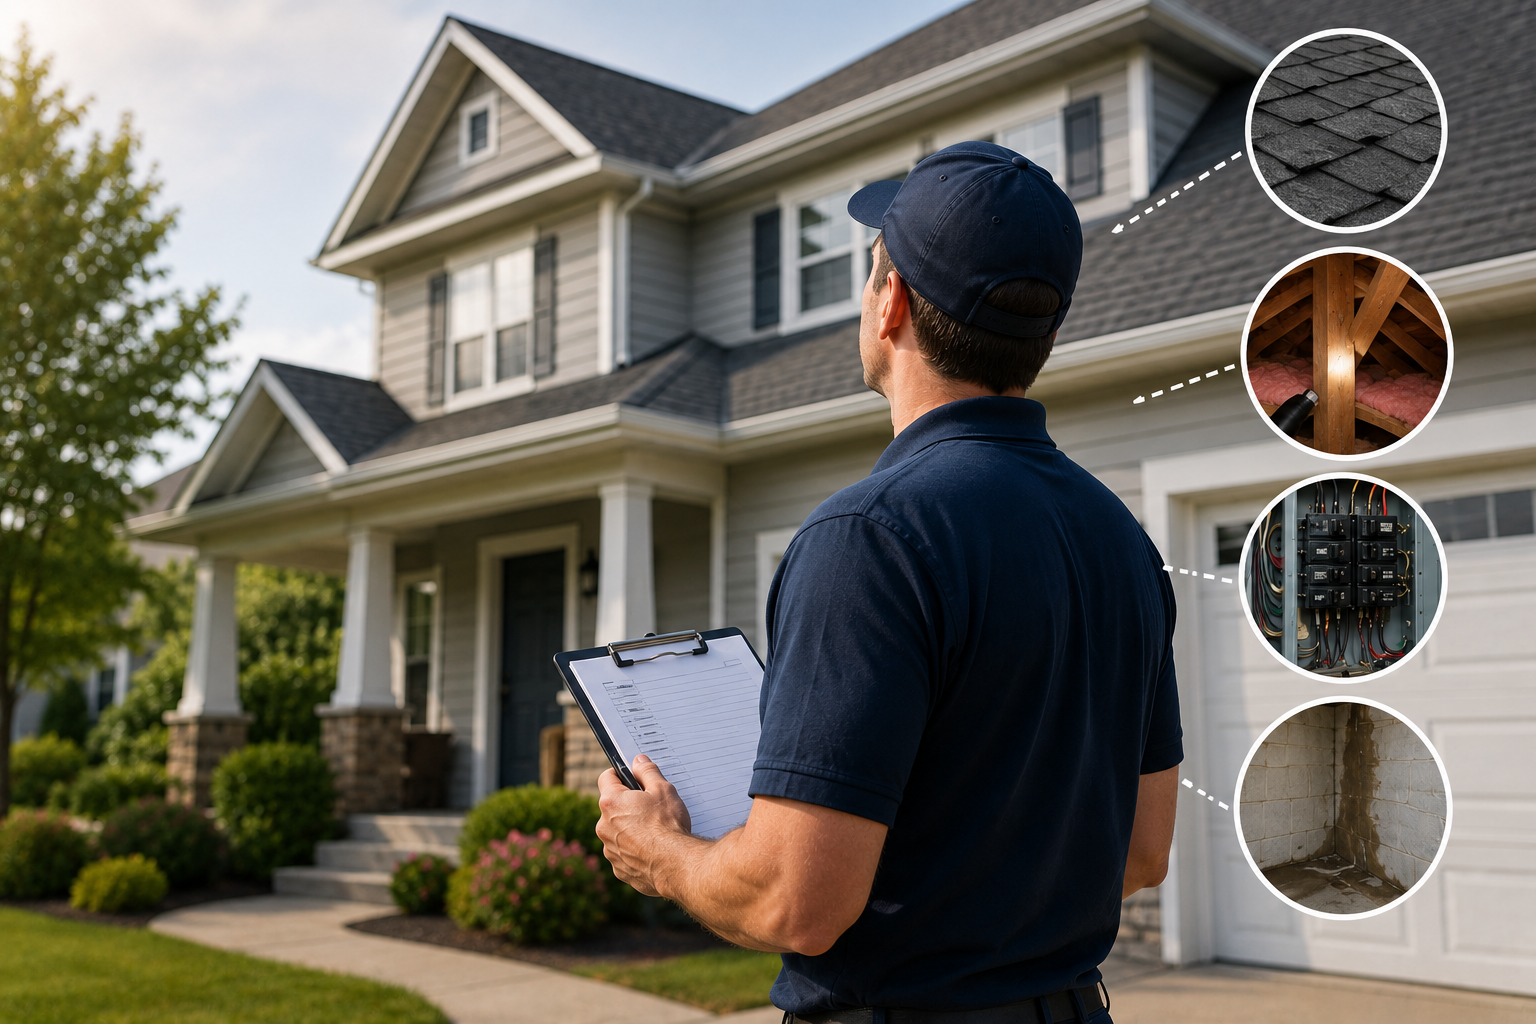
What does a home inspection include? Cost, timing, and what happens after. No fluff advice from a 30-year mortgage veteran for Texas first-time buyers.
LWJ
By Jennifer Hernandez • September 22, 2026
Don't let a locked-up down payment stop your next move. Here's how buy-before-you-sell programs actually work.
LWJ
By Jennifer Hernandez • September 15, 2026
Quitclaim deeds create title problems in Texas. Learn why title companies won't insure them and what Houston homeowners should use instead from a 30-year mortgage pro.
Small house model on financial charts with blue graphs and orange highlights, suggesting real estate analysis for 50 year mortgage
By Jennifer Hernandez • September 8, 2026
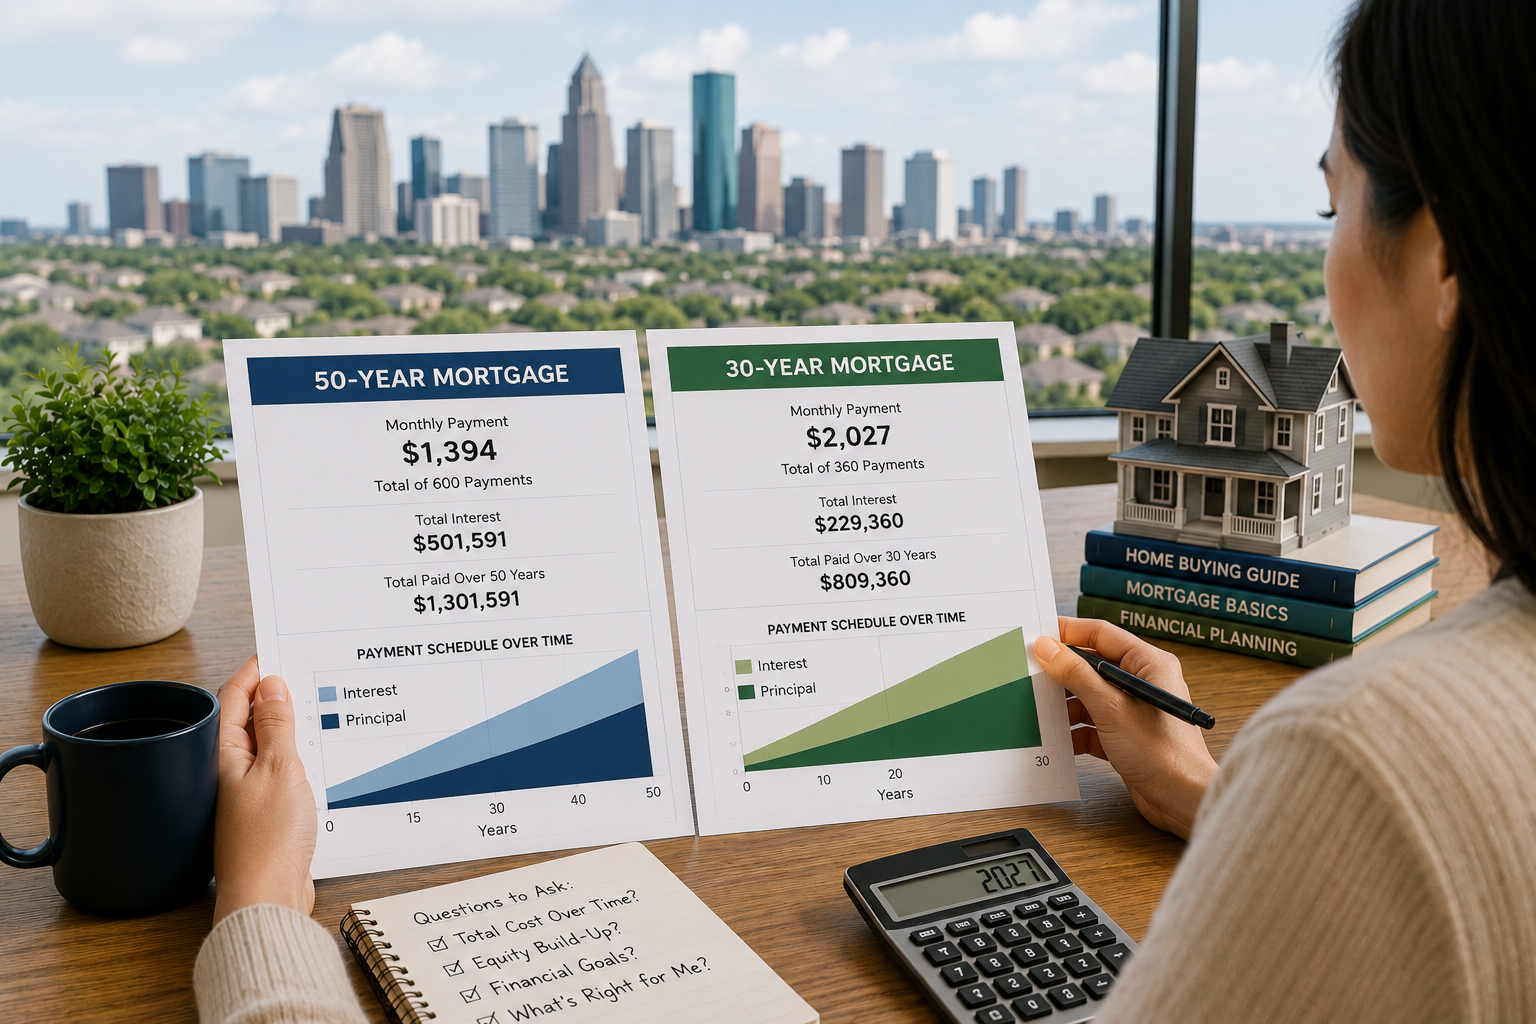
The 50-year mortgage promises lower payments, but is it real and is it smart? A loan officer with 30 years' experience breaks down the true lifetime cost.
Small model house on architectural blueprints with drafting tools on a desk
By Jennifer Hernandez • September 1, 2026
Explore hidden savings on new construction homes. Get expert guidance to maximize your benefits today!
More Posts