
Jennifer Hughes Hernandez is a nationally recognized Senior Loan Officer and Top Producer, building a 100% referral-based business on trust and results since 1995. As host of Emmy-nominated American Dream TV and author of Big Hug Big Kiss, Jennifer combines expertise with a passion for educating homebuyers and supporting realtors through her YouTube channel and coaching events.
How Construction Loans Work: A Step-by-Step Guide for Texas Residents
Jennifer Hernandez • December 27, 2024
Want to build your dream home on land you've purchased or inherited? Construction loans can help bring that vision to life, but understanding how they work is essential to avoid unexpected challenges. This guide explains the key aspects of construction loans, from buying land to financing the building process, and provides tips to make the journey smoother for Texas residents.
Step 1: Purchasing the Land
Before you can begin building, you'll need a piece of land to work with. If you've inherited land, you're already ahead, but if you're purchasing land, there are important details to keep in mind:
- Down Payment Requirements: Land loans require a minimum of 20% down payment. There are no 0% down land loans, so be prepared for this upfront cost.
- Closing Costs: In addition to the down payment, there are closing costs associated with land loans.
Step 2: Choosing a Builder and Designing Your Home
Once you've secured the land, it's time to start planning. This may include finding a builder, working with an architect, and deciding where on the land you'd like to build.
Selecting a reliable builder is a critical step. Many builders, like local Texas builders, offer pre-designed floor plans that can save time and money. However, if you're designing a fully custom home, you'll likely need to work with an architect, which can take several months and add additional costs.
Builders often assist with evaluating your land to determine factors like easements, building restrictions, and other considerations. It's wise to consult with a builder before purchasing land to avoid potential issues, like discovering the land isn't suitable for your desired home.
Remember, custom home designs can take several months to finalize.
Step 3: Understanding Construction Loan Options
Construction loans differ from traditional home loans. Here are the basics:
- Loan Types:
- Conventional Loans: Require as little as 5% down.
- FHA Loans: Require 3.5% down but have loan limits and do not allow for down payment assistance.
- VA Loans: Offer 0% down for eligible veterans.
- No Down Payment Assistance: Construction loans do not qualify for down payment assistance programs, so you'll need savings to cover the required costs.
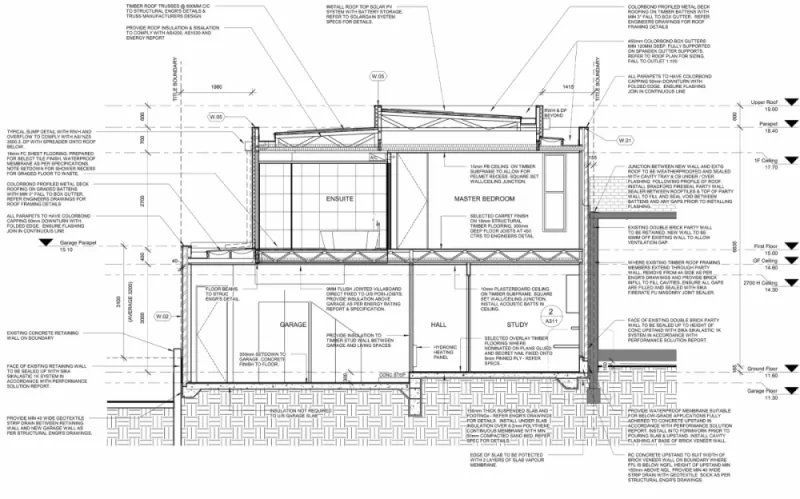
Step 4: Financing the Construction Process
Once you’ve chosen your builder and finalized your home plans, the lender will review and approve the builder’s financials, along with a detailed construction plan. This includes a "draw schedule," outlining when the builder will receive funds throughout the construction process. If you purchased land with a down payment, the amount you’ve paid will typically be credited toward your construction loan.
Here’s an example of how construction loans work:
- Land Purchase: You buy land for $100,000, putting 20% down ($20,000) and financing $80,000.
- Construction Costs: Building your home costs $300,000. The total project cost is now $400,000 (land + construction).
- Loan Financing: If you're using an FHA loan with 5% down, you'll need $20,000 in equity. The $20,000 you put down on the land counts toward this requirement, leaving $380,000 to finance.
During construction, you can expect the loan amount to increase as the builder takes draws to cover the cost of materials, labor, and other expenses. Construction loans are typically interest-only during the construction period, which helps keep payments lower for you while the home is being built.
Step 5: Planning for Extra Costs
When building a home, it's essential to account for contingencies and closing costs. I frequently hear that homeowners change their minds about upgrades and as the building process moves along, changes to materials or locations and sizes of closets are adjusted. These changes add expenses to the contractor's work. To avoid financial stress, lenders require a contingency budget to cover potential overruns. It’s protection for you and for the lender.
Keep in mind, you’ll need to plan for living expenses during construction. Whether you’re renting or paying a mortgage on your current home, you’ll need to budget for both your existing housing costs and the interest payments on the construction loan.
Step 6: Transitioning to a Permanent Loan
Once construction is complete, the loan transitions to a permanent mortgage. At this stage:
- The lender recalculates the loan amount based on the final project cost.
- Payments shift from interest-only to a traditional mortgage payment, typically on a 30-year fixed-rate loan.
Tips for Success with Construction Loans
- Work with Experienced Builders: Look for builders who understand local Texas regulations and offer pre-construction evaluations to avoid surprises.
- Consult a Construction Loan Specialist: Partner with a lender experienced in construction financing to guide you through the process.I’m happy to be your lender of choice!
- Plan for the Unexpected: Always have a financial buffer for contingencies and closing costs.
Resources for Texas Residents
- Learn more about FHA Loans in Texas to see if they’re right for your situation.
- VA Loan Benefits for veterans building homes in Texas.
- Find trusted Texas builders through platforms like NAHB.
Building your dream home is an exciting journey, but it requires careful planning and financial preparation. Understanding the process and partnering with the right professionals can make all the difference. Ready to start? Set up a 15 minute call with me today!
About the Author

Related posts
Read our articles where you can find useful and relevant information about other types of Home Loans:

Learn how to navigate the homebuying process, understand mortgage options, and make confident decisions when buying a home.

Homeowners insurance premiums are skyrocketing across Texas. Discover what’s causing the increase, what you can do to protect yourself, and how to shop smart for coverage in 2025 and beyond.
Explore how sellers are aiding buyers in Houston's market. Get expert guidance to find your dream home today!
What does a home inspection include? Cost, timing, and what happens after. No fluff advice from a 30-year mortgage veteran for Texas first-time buyers.
Don't let a locked-up down payment stop your next move. Here's how buy-before-you-sell programs actually work.
Quitclaim deeds create title problems in Texas. Learn why title companies won't insure them and what Houston homeowners should use instead from a 30-year mortgage pro.
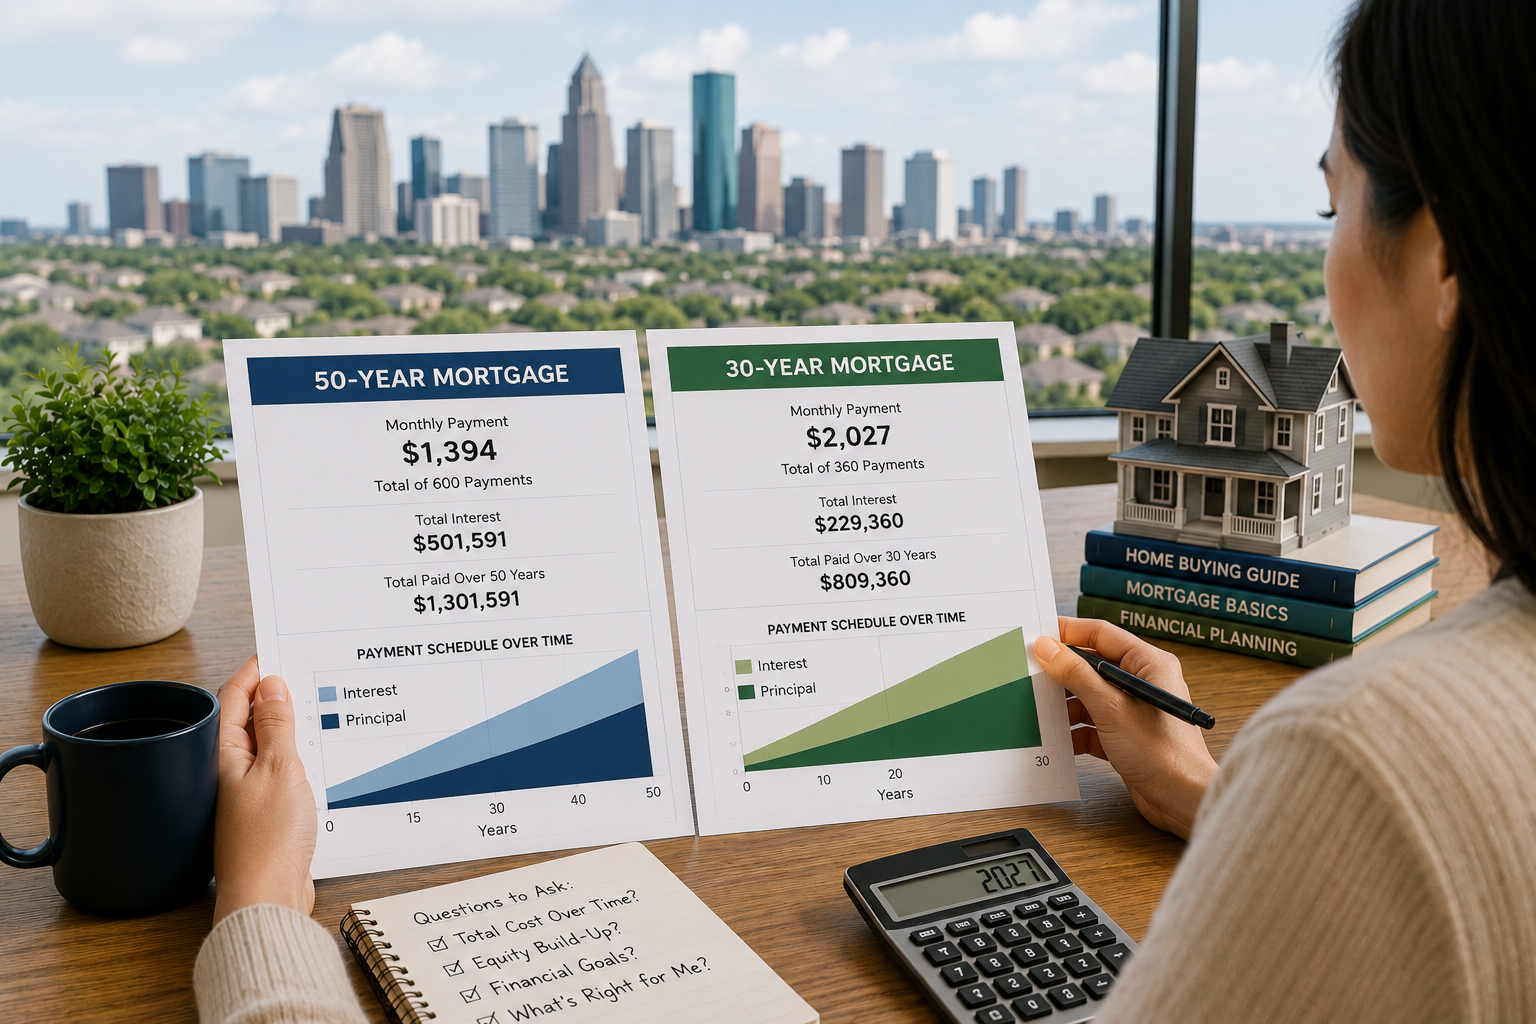
The 50-year mortgage promises lower payments, but is it real and is it smart? A loan officer with 30 years' experience breaks down the true lifetime cost.
Explore hidden savings on new construction homes. Get expert guidance to maximize your benefits today!

Googling mortgage questions? A loan officer gives you personalized answers Google can't. Houston loan officer with 30 years of experience explains why.