Understanding DSCR Loans: A Comprehensive Guide for Texas Investors

Jennifer Hernandez • November 22, 2024

If you're an experienced real estate investor or thinking about purchasing your first investment property, understanding DSCR (Debt Service Coverage Ratio) loans could be your key to unlocking new opportunities.

Today, we’re diving into this unique loan option that is perfect for investment properties.  Throughout  the article, we have listed helpful resource links for Texas investors.


What Is a DSCR Loan?


A DSCR loan is designed for real estate investors and uses the cash flow from an investment property to qualify for financing. This means:

  • No employment or income verification is required.
  • Qualification is based on the property's cash flow rather than the borrower’s personal income.
  • Suitable for short-term rentals and long-term rental properties.

Key Features of DSCR Loans:

  1. Property Cash Flow: The loan qualifies based on whether the rental income covers the mortgage, taxes, insurance, and HOA fees.
  2. Flexible Entity Structures: Borrowers can secure loans under an LLC, even newly formed ones.
  3. Multiple Loan Options: DSCR loans can be used for purchases, rate-and-term refinances, and cash-out refinances.


Why DSCR Loans Are a Game-Changer for Texas Investors


Texas is one of the top states for real estate investment, especially in cities like Houston, Austin, and Dallas. A DSCR loan allows Texas investors to:

  1. Expand their portfolio with minimal documentation.
  2. Access funds through cash-out refinances for future projects.
  3. Simplify qualification by focusing solely on the property’s rental income.

For more information on investment property trends in Texas, visit Texas A&M Real Estate Center.


Steps to Qualify for a DSCR Loan


Here are the basics of how to get started:

  1. Credit Score Requirements: Most lenders require a minimum credit score of 680. For better terms, aim for a 700 or higher.
  2. Down Payment: Typically, borrowers need a 20-25% down payment.
  3. Cash Flow Analysis: A rental income appraisal, called a rent comp analysis, will be ordered to estimate the property’s expected rent.
  4. Reserves: Expect to provide six months of reserves for the subject property.

To discover tailored financing options or loan programs in Texas, click the link below to schedule your 15-minute call:

Book a Call


Key Considerations for DSCR Loans


  1. Loan Terms: Most DSCR loans are available as 30-year fixed-rate mortgages, providing stability for investors.
  2. Loan Amounts: Loan amounts typically range from $75,000 to $1.5 million.
  3. Prepayment Penalty: DSCR loans often come with a three-year prepayment penalty, but you may be able to buy it out for added flexibility.
  4. Rates: Interest rates are slightly higher than conventional loans, but this is balanced by the flexibility DSCR loans offer.

For detailed information on property tax rates across Texas, visit the Texas Comptroller of Public Accounts


Why Work with Local Texas Lenders?


Not all lenders offer DSCR loans, so it’s crucial to partner with a knowledgeable lender who understands Texas markets. Companies like Angel Oak provide a range of non-QM products tailored to investors' needs.

If you're based in Houston or the surrounding areas, explore financing options with Legacy Mutual Mortgage for local expertise.


DSCR loans offer incredible flexibility and opportunity for real estate investors in Texas. Whether you’re looking to purchase your first rental property or refinance an existing portfolio, this loan program simplifies the process by focusing on property cash flow instead of personal income.

Bonus Tip: Interested in exploring other creative financing options? Check out our episode on Bank statement loans — another excellent tool for self-employed borrowers.

Have questions about DSCR loans or other financing options? Reach out to us or explore the resources linked above to make the most informed decision for your investment journey.
Real estate agent showing a bright modern living room to a couple in a sunlit open-plan home
By Jennifer Hernandez • September 29, 2026
Explore how sellers are aiding buyers in Houston's market. Get expert guidance to find your dream home today!
LWJ
By Jennifer Hernandez • September 22, 2026
What does a home inspection include? Cost, timing, and what happens after. No fluff advice from a 30-year mortgage veteran for Texas first-time buyers.
LWJ
By Jennifer Hernandez • September 22, 2026
Don't let a locked-up down payment stop your next move. Here's how buy-before-you-sell programs actually work.
LWJ
By Jennifer Hernandez • September 15, 2026
Quitclaim deeds create title problems in Texas. Learn why title companies won't insure them and what Houston homeowners should use instead from a 30-year mortgage pro.
Small house model on financial charts with blue graphs and orange highlights, suggesting real estate analysis for 50 year mortgage
By Jennifer Hernandez • September 8, 2026
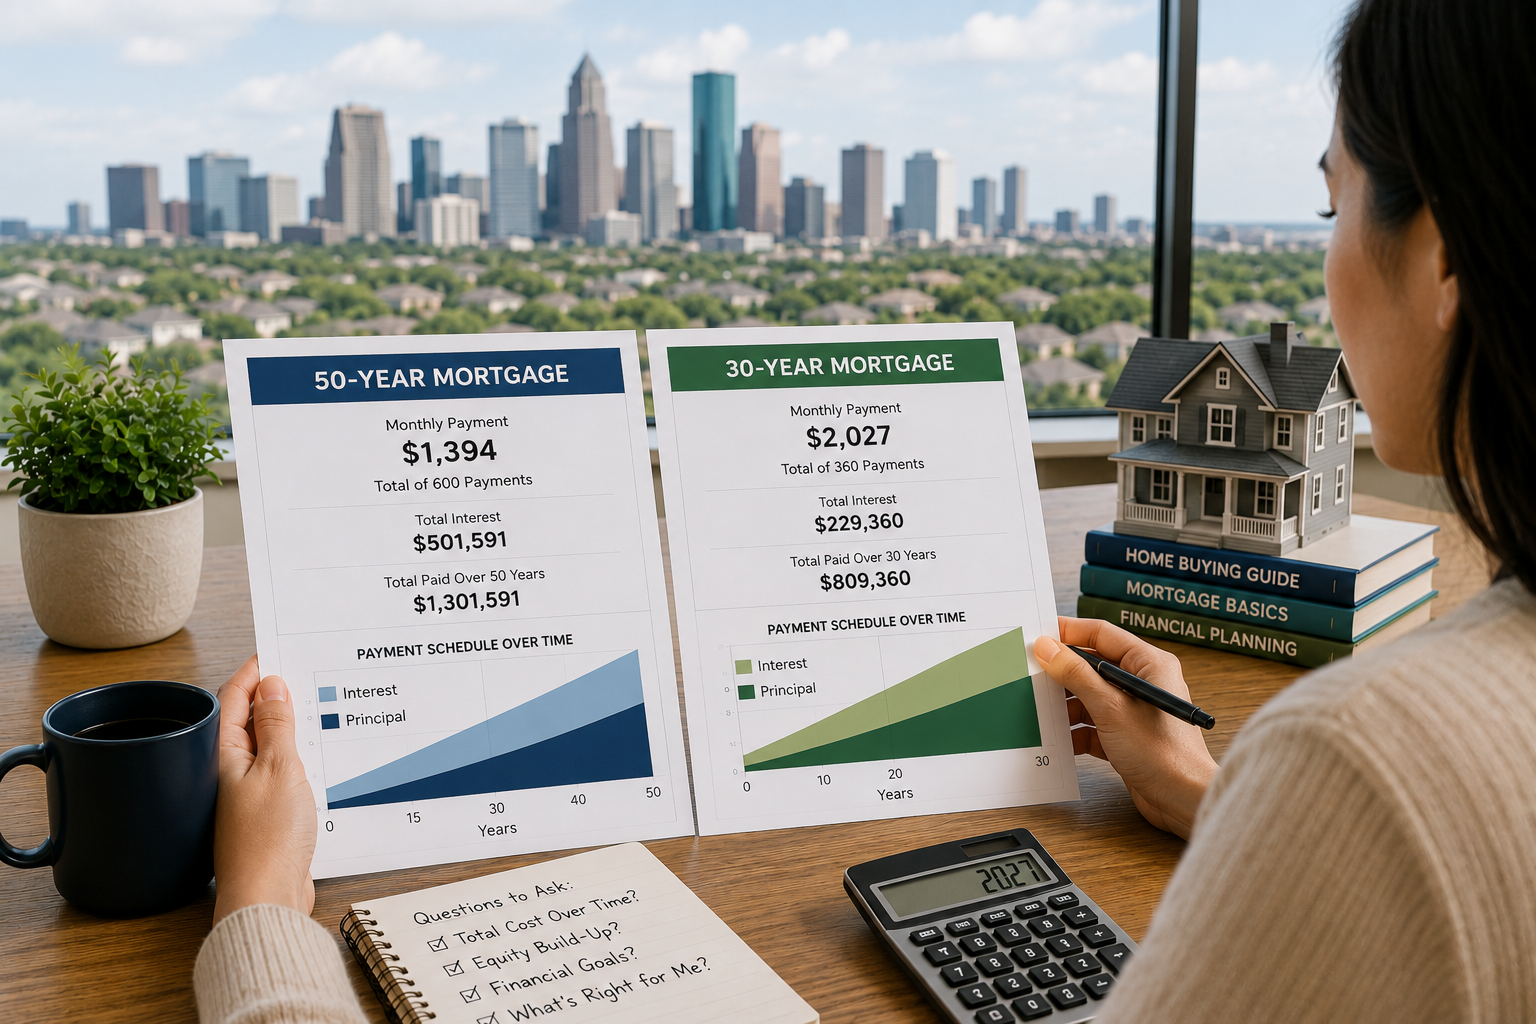
The 50-year mortgage promises lower payments, but is it real and is it smart? A loan officer with 30 years' experience breaks down the true lifetime cost.
Small model house on architectural blueprints with drafting tools on a desk
By Jennifer Hernandez • September 1, 2026
Explore hidden savings on new construction homes. Get expert guidance to maximize your benefits today!
Three people, a realtor and 2 first time buyers discuss documents at a laptop during a meeting in a bright office
By Jennifer Hernandez • August 18, 2026
Googling mortgage questions? A loan officer gives you personalized answers Google can't. Houston loan officer with 30 years of experience explains why.
Keys resting on a stack of papers beside a binder in soft light
By Jennifer Hernandez • August 11, 2026
Learn about seller credits & rate buydowns for Houston homebuyers. Get the best incentives to save on your first home purchase!
By Jennifer Hernandez • August 4, 2026
You've been looking at homes for months. Your sister offers to go in with you. Or your partner says let's do this together. Or a parent says, I'll help you qualify. Or a friend says we should buy a rental property. Suddenly that home you couldn't afford alone becomes possible. Co-owning property can absolutely be a smart move. It can get you into a home sooner, help you build equity faster, and turn a “ maybe someday ” into “ We're doing this! I've seen it work beautifully for hundreds of families over the years. But I've also seen it go sideways. Not because people had bad intentions, but because they skipped the hard conversations and left the details to chance. When co-ownership isn't structured right from the start, it doesn't just cause tension. It can turn into an expensive, exhausting legal mess that takes years to untangle. Here's what you need to know before you sign anything.
More Posts