Every week we release educational videos related to hot topics in the mortgage industry on YouTube.
Subscribe to our channel to stay in-the-know!
This information could save you thousands of dollars. Not all credit scores are FICO scores, and to complicate things even further, there are over three dozen versions of FICO! If you’re planning to buy a home soon and are concerned about your credit score, keep reading—I’m breaking down the real facts. No fluff, just the essential details you need to know.
As a mortgage loan officer with nearly three decades of experience, I’ve seen it all. Every week, I ask new clients what they think their credit score is. Without fail, the number they provide is different from the actual score I pull. Sometimes it’s just a few points off, but I’ve also seen differences of 100 points or more! Why does this happen? Credit scores are highly individualized, and not all scores are calculated the same way.
Here’s the good news—I’ve been pulling credit reports since mortgage companies began using FICO scores. I’ve learned how to navigate this complicated world, and I’m here to share what you need to know.
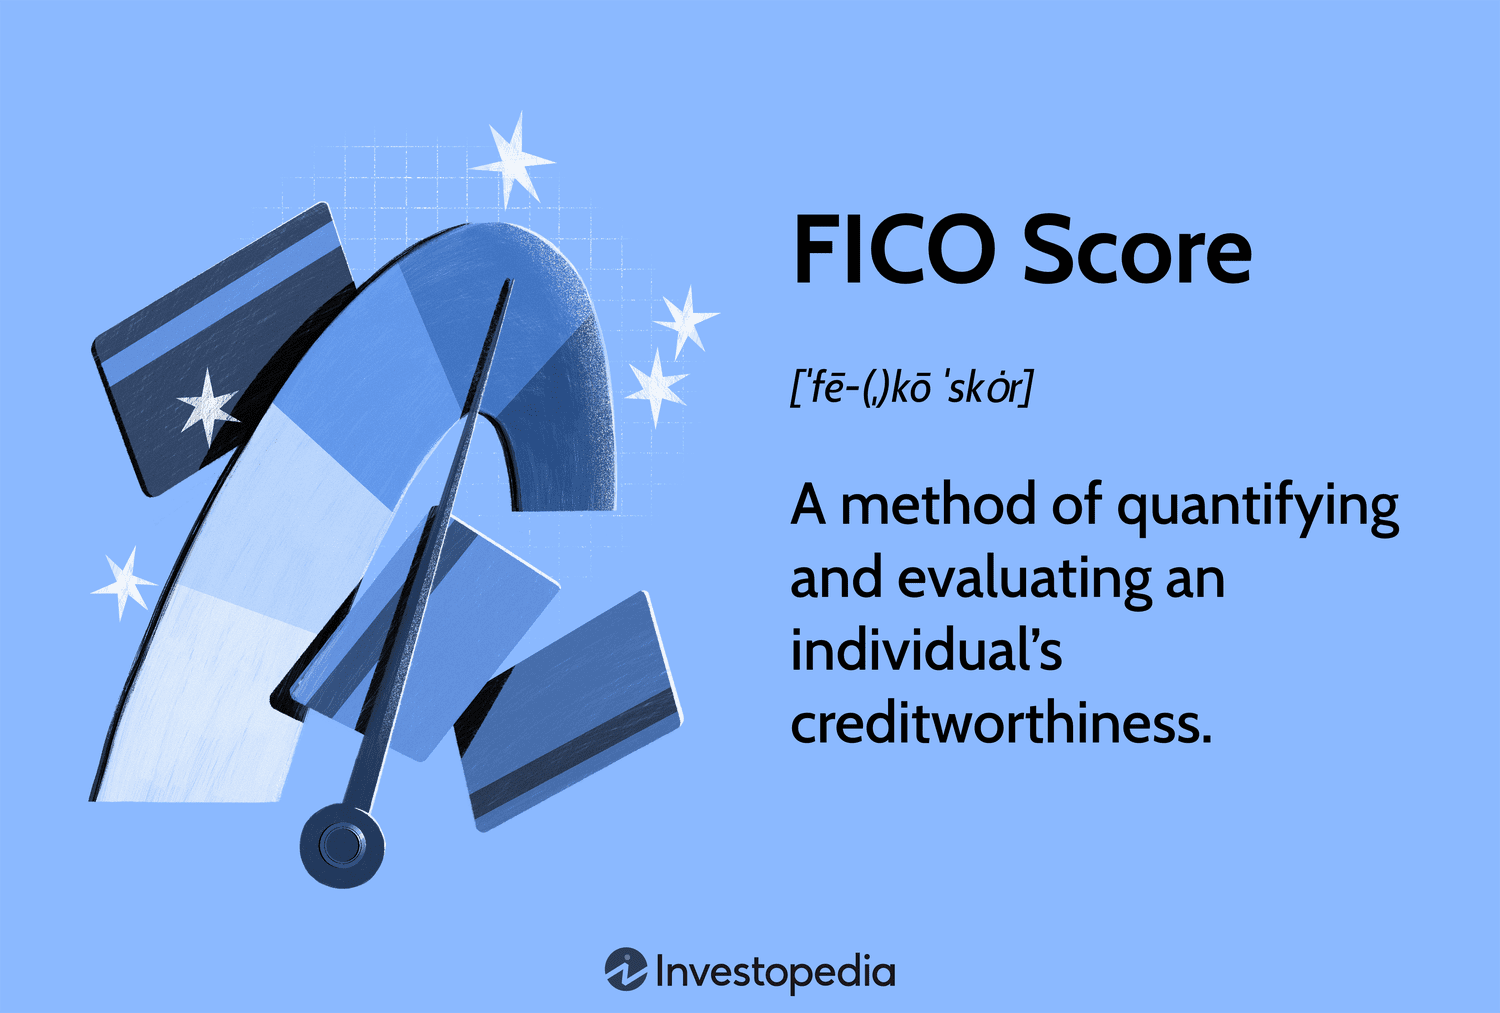
A FICO score is a three-digit number calculated using data from the three main credit bureaus: Equifax, Experian, and TransUnion. But where did FICO come from?
FICO (Fair Isaac Corporation) became the standard for credit scoring in 1989, using its advanced algorithm to assess credit risk. To learn more about the history of credit scores and the credit bureaus, check out my blog. But here’s where things get tricky—there are more than 36 versions of FICO, each designed for different purposes!
For example:
Every time a new version of FICO is released, companies must decide whether to upgrade—and it costs money to update. Most free credit score services you see from your bank or credit card issuer may not be using the latest version, or even a FICO score at all. This is why the score you see as a consumer often differs from the one your lender sees.
When it comes to buying a home, your mortgage FICO score plays a critical role in determining your loan eligibility, interest rate and even private mortgage insurance amount.
Why does this matter? A lower score could mean a higher interest rate, potentially costing you thousands of dollars over the life of your loan.
Related Resource: Learn more about FHA Loans and credit requirements
If you’re thinking about buying a home in the next 12 months, the best way to get an accurate picture of your credit is to have a mortgage lender pull your credit report. While consumer credit scores are helpful for general monitoring, they won’t give you the full story.
Pro Tip: Multiple mortgage credit pulls within a 30-day window count as a single inquiry for scoring purposes, so don’t be afraid to shop around for the best lender.
Want to increase your score before applying for a mortgage? Focus on these key areas:
If you’ve had a late payment or collection in the last 12 months, it can cause your score to drop 50–100 points. Pay all your bills on time to avoid this penalty.
This refers to the percentage of your credit limit that you’re using. To improve your score:
Example: If your credit limit is $1,000, try to keep your balance below $300.
Avoid closing old accounts, as this can shorten your credit history and lower your score.
For more tips, watch my YouTube video on credit utilization and how it impacts your mortgage.
The most important takeaway is this: What you see as a consumer is not the same as what your lender sees. If you’re planning to buy a home, work with a mortgage lender early on to understand your true credit picture and take the necessary steps to improve it.
Related Resources:
Ready to take the next step? Contact me at Loan with Jen for personalized advice and a plan to boost your credit score for home buying success.



All Rights Reserved | Jennifer Hughes Hernandez | Senior Loan Officer | NMLS #514497
Full service residential lender with an experienced team offering expert service, reliable communications and on-time closings in the greater Houston area.
Every week we release educational videos related to hot topics in the mortgage industry on YouTube.
Subscribe to our channel to stay in-the-know!
Gardner Financial Services, Ltd., dba Legacy Mutual Mortgage, NMLS #278675, a subsidiary of Prosperity Bank. 18402 U.S. Highway 281 N, Ste. 258, San Antonio, TX 78259. AZ BK-2001467. Check registration and licensing at nmlsconsumeraccess.org. Legacy Mutual Mortgage is an Equal Housing Lender. This is not a commitment to lend. Material is informational only and should not be construed as investment or mortgage advice. Legacy Mutual Mortgage is not an agency of the federal government. Not all loan products are available in all states. All loans are subject to credit and property approval. Not all applicants qualify. Restriction and conditions may apply. Information and programs current as of date of distribution but may change without notice. [11/2025]