Does a Hard Inquiry on Your Credit Really Hurt Your Score?

Jennifer Hernandez • March 24, 2025

Does a Hard Inquiry on Your Credit Really Hurt Your Score?

If you're planning to buy a home in Texas, you may be wondering: Does a hard inquiry on your credit really damage your score, and how will it affect your chances of mortgage approval? Let's break down what a hard inquiry is, how it impacts your credit, and strategies to minimize its effect so you can confidently move forward with your home purchase.


What is a Hard Inquiry?


A hard inquiry occurs when a lender checks your credit report to assess your creditworthiness for a loan, credit card, auto loan, or mortgage. Unlike soft inquiries (which happen when you check your own credit or when a lender pre-qualifies you without a formal application), hard inquiries are recorded on your credit report and may impact your credit score.

Inquiries remain on your credit report for up to two years, but the good news is that FICO scoring models (used by 90% of lenders) only consider them for one year. This means that while the inquiry stays visible on your report, its impact on your score diminishes after 12 months.


How Hard Inquiries Affect Your Mortgage Approval


A hard inquiry alone is unlikely to prevent you from getting pre-approved for a mortgage. However, here’s what you need to know:

  • FICO Treats Multiple Mortgage Inquiries as One: If multiple mortgage lenders pull your credit within a 30-day window, it only counts as one inquiry for scoring purposes. This allows you to shop for the best mortgage rates without penalty.
  • Other Inquiries Can Hurt Your Score: While mortgage inquiries are grouped together, applying for credit cards, auto loans, or personal loans during the same time frame can lower your score.
  • Impact Depends on Your Existing Credit Score: If your credit is already strong (e.g., 700+ score), a hard inquiry may have a minimal effect—think of it as a small “peck” on a steel building. However, if your credit is already struggling, an additional inquiry could have a more noticeable impact.

👉 For a deeper dive into credit scores and mortgages, check out Loan with Jen’s guide on mortgage pre-approvals.


Three Ways to Minimize the Impact of Hard Inquiries


  1. Time Your Mortgage Credit Pulls Wisely
  • If you’re shopping for a mortgage, make sure all inquiries happen within the same 30-day period to be counted as a single inquiry.
  1. Avoid Applying for Other Types of Credit
  • Do not apply for credit cards, car loans, or other financing right before or during the mortgage approval process.
  1. Monitor Your Credit with Trusted Sources
  • Not all credit score models are the same. For the most accurate mortgage-related credit score, use MyFICO rather than free sites like Credit Karma, which may use different scoring models.


Key Takeaways


  • A hard inquiry alone won’t make or break your mortgage approval—but excessive inquiries across different credit types can have a greater impact.
  • Mortgage inquiries within 30 days are grouped as one, so shop around for lenders without fear of multiple credit hits.
  • Your current credit standing matters—higher scores will see less impact from inquiries, while lower scores could experience more significant drops.
  • Use reputable credit monitoring services to stay informed about your credit health.

For more expert mortgage advice, check out the Loan with Jen YouTube channel where we cover all things home financing!

Ready to start your home-buying journey in Texas? Get personalized mortgage advice by booking a call with me.
BOOK A CALL
LWJ
By Jennifer Hernandez September 15, 2026
Quitclaim deeds create title problems in Texas. Learn why title companies won't insure them and what Houston homeowners should use instead from a 30-year mortgage pro.
Small house model on financial charts with blue graphs and orange highlights, suggesting real estate analysis for 50 year mortgage
By Jennifer Hernandez September 8, 2026
The 50-year mortgage promises lower payments, but is it real and is it smart? A loan officer with 30 years' experience breaks down the true lifetime cost.
Small model house on architectural blueprints with drafting tools on a desk
By Jennifer Hernandez September 1, 2026
Explore hidden savings on new construction homes. Get expert guidance to maximize your benefits today!
Three people, a realtor and 2 first time buyers discuss documents at a laptop during a meeting in a bright office
By Jennifer Hernandez August 18, 2026
Googling mortgage questions? A loan officer gives you personalized answers Google can't. Houston loan officer with 30 years of experience explains why.
Keys resting on a stack of papers beside a binder in soft light
By Jennifer Hernandez August 11, 2026
Learn about seller credits & rate buydowns for Houston homebuyers. Get the best incentives to save on your first home purchase!
By Jennifer Hernandez August 4, 2026
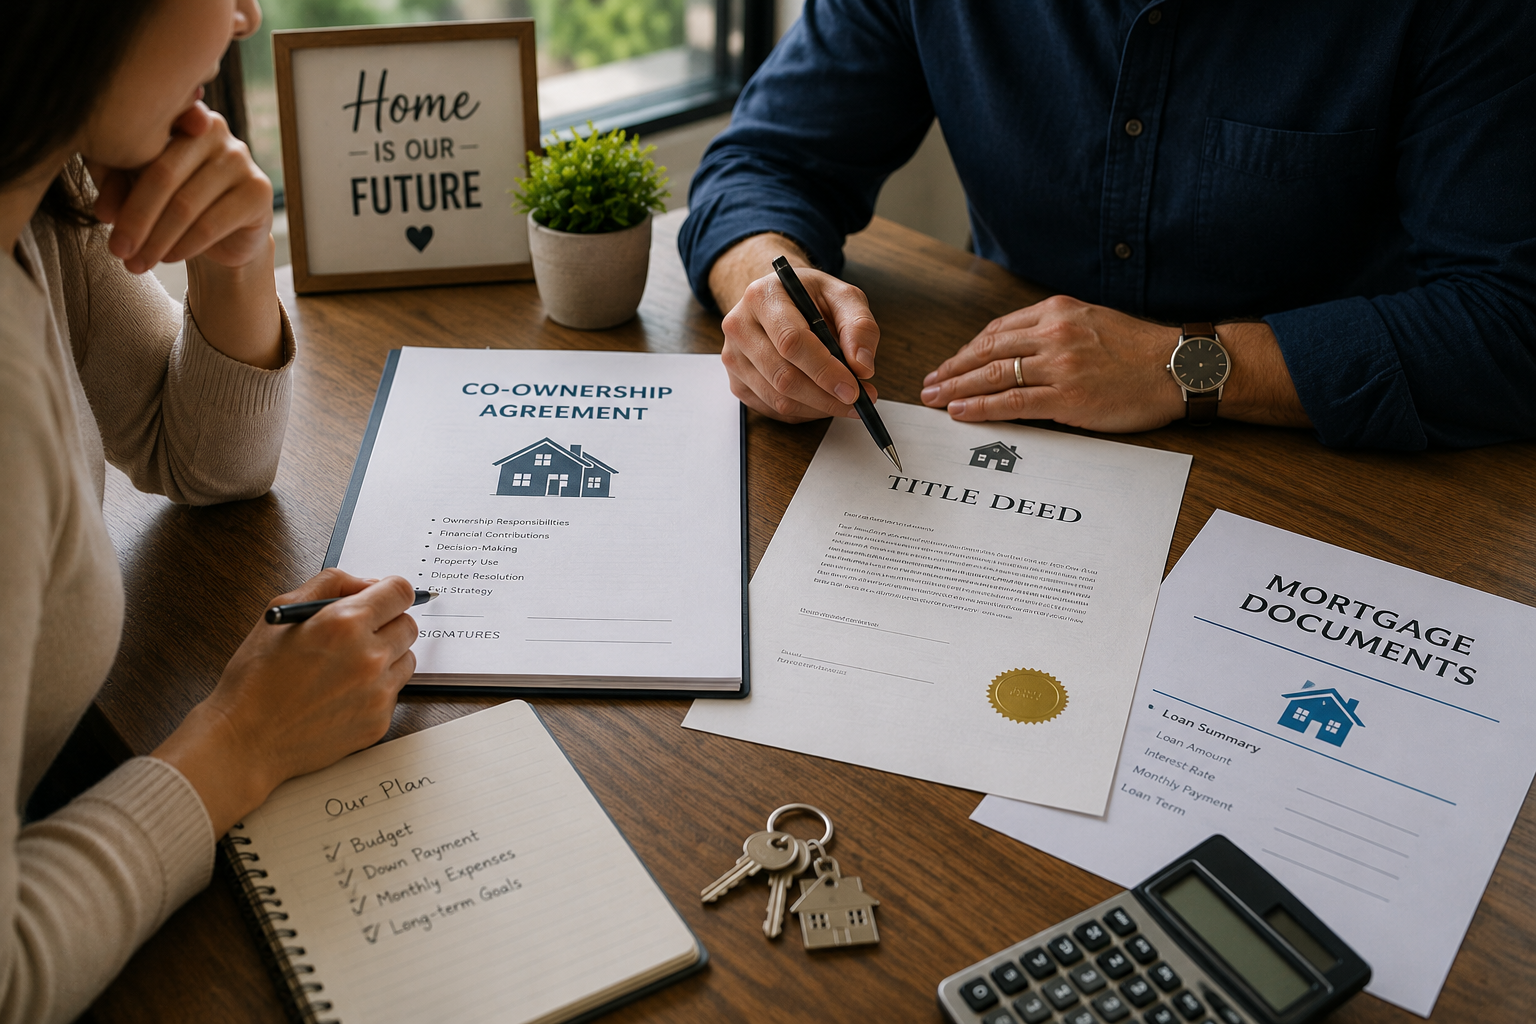
You've been looking at homes for months. Your sister offers to go in with you. Or your partner says let's do this together. Or a parent says, I'll help you qualify. Or a friend says we should buy a rental property. Suddenly that home you couldn't afford alone becomes possible. Co-owning property can absolutely be a smart move. It can get you into a home sooner, help you build equity faster, and turn a “ maybe someday ” into “ We're doing this! I've seen it work beautifully for hundreds of families over the years. But I've also seen it go sideways. Not because people had bad intentions, but because they skipped the hard conversations and left the details to chance. When co-ownership isn't structured right from the start, it doesn't just cause tension. It can turn into an expensive, exhausting legal mess that takes years to untangle. Here's what you need to know before you sign anything.
Futuristic analytics dashboard with circular center gauge and floating data charts on blue background
By Jennifer Hernandez July 31, 2026
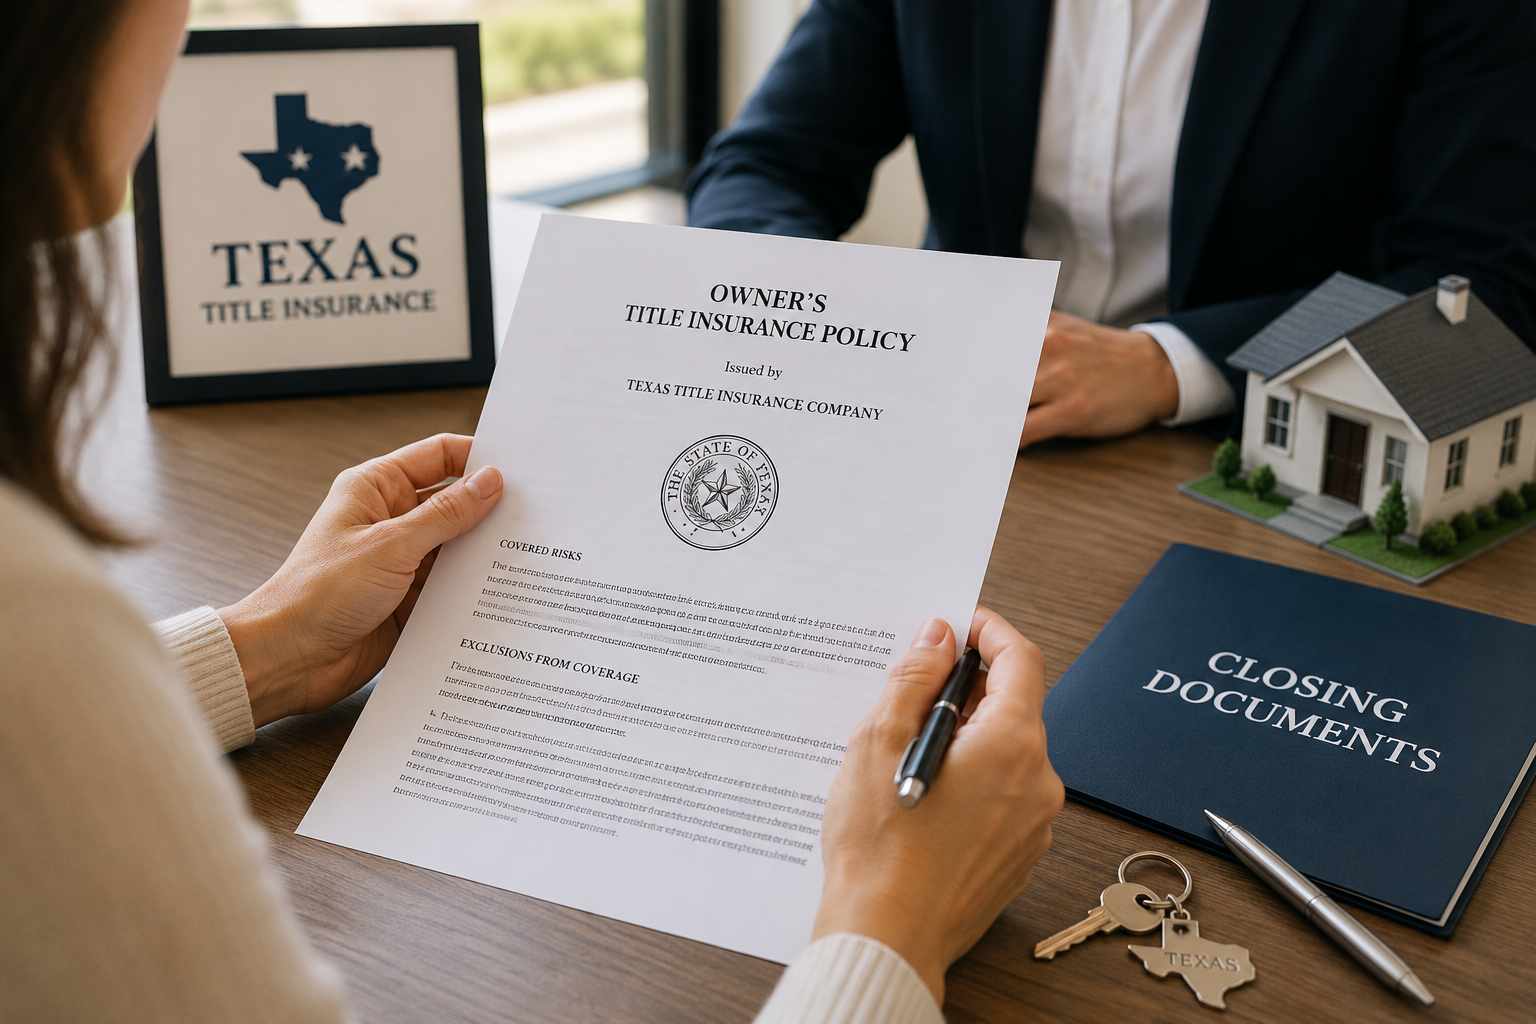
Title insurance in Texas explained by a loan officer with 30 years' experience: what it protects, why rates are state-set, and who pays at closing.
An empty nest couple reviewing paperwork for downsizing in Houston to a smaller home
By Jennifer Hernandez July 24, 2026
Texas seniors can now exempt up to $200,000 from school taxes and transfer their tax freeze to a new home. Before buying a townhome or 55+ condo, ask these three HOA questions. Get smart downsizing tips from Houston loan officer Jen Hughes Hernandez.
More Posts