Every week we release educational videos related to hot topics in the mortgage industry on YouTube.
Subscribe to our channel to stay in-the-know!
You opened seventeen browser tabs last night.
One compares FHA to conventional loans. Another about credit scores and down payments. A Reddit thread from 2023 where someone with kind of similar finances to yours got approved but also maybe didn't. A mortgage calculator that gave you three different answers depending on which boxes you checked. And a forum post about PMI that honestly just made you more confused.
I've been doing this for thirty years. I can tell you exactly when someone walks into my office after spending weeks trying to piece together their mortgage strategy from search results and YouTube videos. They're exhausted. They're overwhelmed. And they usually have at least two things wrong.
Here's what I tell them and what I'm telling you now: you don't have to figure this out alone. That's what I'm here for.
Generic mortgage advice has a problem. It can't see you.
It doesn't know that you've got a student loan in deferment that might or might not count against your debt ratio depending on the loan type. It doesn't know your spouse is switching from hourly to salaried next month or that you've got a medical collection from 2021 that's about to age off your credit report. It can't tell you whether the home you want in Pearland is going to appraise in this market or if you'd be better off waiting ninety days to improve your loan terms.
Every buyer's situation is different. Your income structure matters. Your credit history matters. The specific property you're buying matters. What worked for someone in a forum thread three years ago might not apply to you at all.
You can spend hours reading about down payment requirements and still not know which program you actually qualify for today.
Here's what almost nobody tells you: answering your questions is a huge part of my job. Not just tolerated. Not just expected. It's actually one of the most important things I do.
When you call me to ask whether you should pay off that credit card before you apply, or whether your freelance income is going to be a problem, or if that gap in employment two years ago matters, I'm not annoyed. I'm gathering information I need to get you the best loan possible.
The more you tell me, the better I can help you. The more questions you ask, the fewer surprises we'll hit during underwriting.
I would rather spend twenty minutes on the phone with you now explaining how tax returns affect self-employed income verification than have you spend six hours online trying to interpret guidelines that might not even apply to your loan type. I've worked with thousands of families over three decades. I've seen every scenario. The thing you're worried about? I've probably helped ten people through it this month alone.
Online calculators give you estimates. I give you a plan.
When you sit down with me, I'm looking at your full financial picture. I can tell you exactly where you stand right now, what loan programs you qualify for, and if there's anything you should adjust before we submit your application. If you're not quite ready yet, I'll tell you that too—even when it means waiting sixty days and not earning anything from you right now.
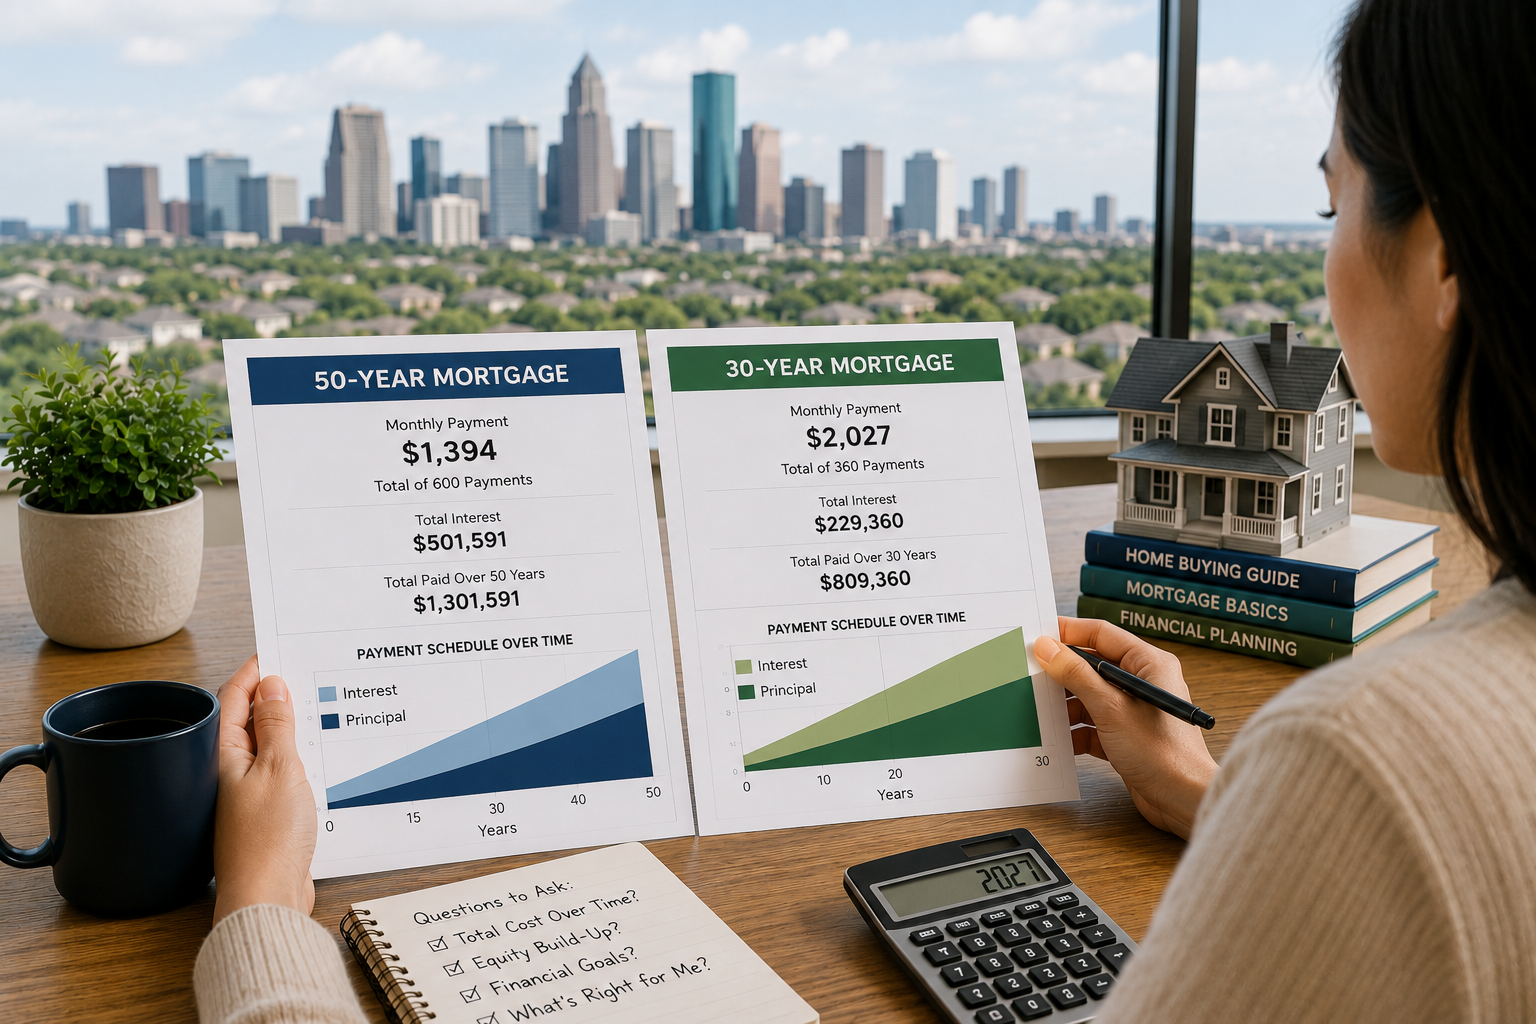
That's the difference between information and advice. Information tells you the minimum credit score for an FHA loan. Advice tells you that with your profile, waiting four months to pay down your auto loan will save you $83 a month for thirty years.
For Houston buyers especially, this matters. Property taxes here are higher than a lot of people expect. Flood zone requirements can affect your loan type and insurance costs. Some neighborhoods are seeing multiple offers within 24 hours, which means you need a preapproval that's rock-solid, not a prequalification letter you printed off a website.
I can also steer you away from mistakes before they happen. I've stopped clients from buying cars three weeks before closing. I've caught credit report errors that would have killed their loan. I've walked people through job changes and financial hiccups that seemed like disasters but turned out to be manageable with the right documentation.
You don't get that from a search engine.
You can keep researching, or you can get real answers.
I'm not saying don't educate yourself. It's smart to understand the basics before we talk. But there's a point where more Googling just adds to the confusion instead of clearing it up. And if you're already feeling overwhelmed, you've probably hit that point.
The mortgage process has plenty of real stress built in. Don't add unnecessary anxiety by trying to become a lending expert in two weeks.
The right guidance can help you replace confusion with confidence and make smarter decisions throughout your homebuying journey.
All Rights Reserved | Jennifer Hughes Hernandez | Senior Loan Officer | NMLS #514497
Full service residential lender with an experienced team offering expert service, reliable communications and on-time closings in the greater Houston area.
Every week we release educational videos related to hot topics in the mortgage industry on YouTube.
Subscribe to our channel to stay in-the-know!
Gardner Financial Services, Ltd., dba Legacy Mutual Mortgage, NMLS #278675, a subsidiary of Prosperity Bank. 18402 U.S. Highway 281 N, Ste. 258, San Antonio, TX 78259. AZ BK-2001467. Check registration and licensing at nmlsconsumeraccess.org. Legacy Mutual Mortgage is an Equal Housing Lender. This is not a commitment to lend. Material is informational only and should not be construed as investment or mortgage advice. Legacy Mutual Mortgage is not an agency of the federal government. Not all loan products are available in all states. All loans are subject to credit and property approval. Not all applicants qualify. Restriction and conditions may apply. Information and programs current as of date of distribution but may change without notice. [11/2025]